All Categories
Featured
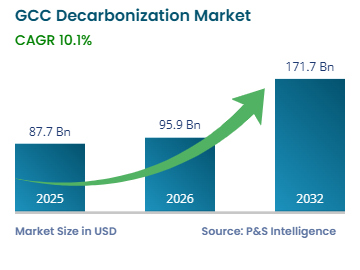
Rather than marking a cyclical rebound, 2026 is significantly viewed as a consolidation year, in which diversification-led development becomes more deeply ingrained in the area's economic model, lowering reliance on hydrocarbons and increasing durability to external shocks. Projections from major organizations broadly assemble on a more powerful GCC development profile in 2026 than in 2025, supported by resistant domestic need, continued non-oil growth, and (to differing degrees) a firmer hydrocarbon contribution.
3.2 percent growth in 2025, speeding up to 4.5 percent in 2026. Sees momentum improving, with GCC output development projected to increase from 1.7 percent in 2024 to 3.3 percent on average in 2025, showing a shift towards more positive general conditions.
Traditional Vs Global Approaches in the GCC RegionThe IMF's World Economic Outlook (October 2025) projects international development reducing to 3.1 percent in 2026, with sophisticated economies around 1.5 percent and emerging market and developing economies simply above 4 percent. On that comparison, a 4.44.5 percent GCC growth would place the region materially ahead of the world average and somewhat above (or broadly in line with) the emerging-market aggregate, enhancing the GCC's status as a reasonably high-growth pocketprovided that regional risk conditions remain included and reform momentum holds.
Information from the GCC Statistical Center show that non-oil sectors already represent more than 73 percent of overall GDP, a share that has actually continued to rise as federal governments broaden investment in services, infrastructure, and technology. According to Oxford Economics, non-energy activity across the GCC is projected to grow by around 4.1 percent in 2026, supported by strong labor markets, improving credit conditions, and rising financial investment in technology and AI-related infrastructure.
Operational Excellence: a Key Driver for 2026 Success
Public-sector investment and reform remain central to sustaining this pattern. Policy procedures targeted at drawing in foreign direct investment, easing foreign ownership rules, broadening capital markets, and supporting private-sector participation continue to underpin non-oil growth and decrease the region's direct exposure to oil price volatility. While hydrocarbons no longer control the development outlook, oil incomes are anticipated to play an encouraging function in 2026.
Oxford Economics anticipates Brent crude prices to fall listed below USD 60 per barrel in early 2026, limiting the near-term contribution of oil extraction to GDP. Oil supply is forecast to rise once again in the second half of the year, with a full unwinding of staying production caps likely by mid-2027.
Macroeconomic conditions across the GCC stay broadly supportive of development. Inflation is expected to remain low, with the IMF forecasting typical inflation of 2 percent across the region in 2026. Steady prices are helping maintain genuine family incomes and underpin consumer spending, which Oxford Economics expects to grow by approximately 3.5 percent over 20262027.

Latest Posts
How Future-Focused Strategy Reshapes the GCC Economy
Unlocking Operational Excellence in Dubai's Industrial Sector
Sustainable Regional Industrial Growth Models in 2026